Average age of accounts (AAoA) is the mean age of every tradeline on your credit report, both open and some closed ones, calculated in months and years. If you're deciding where to spend your energy, pay on time and keep balances low first. AAoA is the tweak, not the fix.
TL;DR:
- Opening a new account reduces your average account age immediately, especially if you have few existing tradelines, but closing accounts retains their history for years.
- AAoA accounts for approximately 15% of FICO scores, but payment history and utilization have a larger influence on your overall credit score.
- Life events like marriage, divorce, or moving can cause short-term drops in AAoA due to new tradelines or account closures, but these are usually temporary.
- Prioritizing on-time payments and low balances matters more than obsessing over the AAoA number, which generally improves naturally over time.
- Using an AI credit coach can help manage account age, balances, and timing, preventing costly mistakes and providing clear insights tailored to your credit profile.
Table of Contents
- What Average Age of Accounts Means and How It's Calculated
- How Account Age Affects Your Score, and How Much It Really Weighs
- Opening or Closing an Account Changes Your Average, Here's How
- A Priority Checklist for Managing Account Age
- How an AI Credit Coach Helps You Balance Age, Utilization, and Timing
- FICO and VantageScore Don't Weigh Account Age the Same Way
- What Counts as a Good Average Account Age
- Why Account Age Only Matters Alongside Your Other Credit Factors
- The Myths About Account Age That Cost People Points
- How Marriage, Divorce, and Moving Can Shift Your Account Age
- Stop Chasing the Age Number, Start Fixing What Actually Drives Your Score
- Manage Every Card's Age and Payment Timing in One Place
- Sources
- FAQ
What Average Age of Accounts Means and How It's Calculated
Every account you have ever opened, and some you've closed, carries an age measured from its open date to today (or to its closure date, if it's no longer active). AAoA adds up the ages of all those tradelines and divides by the number of accounts.
Here's the math in plain terms: say you have three accounts. One is 10 years old, one is 4 years old, and one is 8 months old. Add those ages together (10 + 4 + 0.67 years), divide by three, and you land around 4.9 years. Open a fourth account today and that new zero-month tradeline drags the average down immediately, even though your oldest account hasn't changed at all.
You can check your own AAoA and the individual account ages behind it using a few resources:
- Your credit report from each of the three bureaus, pulled through AnnualCreditReport.com, which lists open dates for every tradeline.
- Free credit monitoring tools offered by many banks and card issuers, which often surface a length-of-history metric directly.
- Experian's account history breakdown, which shows average account age alongside your oldest and newest accounts.
How Account Age Affects Your Score, and How Much It Really Weighs
Length of credit history, the category that includes AAoA, makes up about 15% of many FICO scoring models. That's a real slice of the pie, but it's smaller than payment history and amounts owed combined, which together drive well over half your score.
Length of credit history accounts for roughly 15% of many FICO scores, according to CFPB's own scoring breakdown. Payment history and utilization still carry far more weight.
This category isn't just AAoA on its own. Scoring models also weigh the age of your oldest account and the time since you opened your most recent one, three related but distinct numbers that Experian explicitly lists as inputs.
The interaction matters more than the raw number. A 12-year-old account with a couple of 60-day late payments buried in its history can hurt you more than a spotless 3-year-old account helps you. The CFPB frames credit scores as estimates of repayment risk, so a long history only pays off when it shows a pattern of paying on time. A short, clean history with perfect payments often scores better than a long one with blemishes.
Opening or Closing an Account Changes Your Average, Here's How
Every new account you open starts its life at zero months old. That immediately pulls your average down, even if the account itself is a smart financial move. The size of the dip depends on how many accounts you already have. Adding a new card when you have two others is a bigger hit than adding one when you have eight.
Closing an account doesn't erase it right away. Closed accounts can remain on your credit report and continue influencing your average for a while, and negative information tied to an account can generally stay reportable for up to seven years. Positive history from a closed account doesn't vanish overnight either.
Some practical trade-offs to weigh before you close anything:
- Keeping a no-fee card open, even one you rarely use, preserves both its age and your total available credit.
- Closing a card mainly to escape an annual fee makes sense if the fee outweighs the age benefit, but check whether the issuer will waive it first.
- If a card has been compromised or you no longer trust the issuer, closing it for security reasons can outweigh the AAoA cost.
Verify exact open and closure dates through AnnualCreditReport.com or by pulling reports directly from each bureau. The dates listed there are what scoring models actually use, not your memory of when you signed up.
A Priority Checklist for Managing Account Age
Most people worry about AAoA in the wrong order. Fix these in sequence, and the age number tends to take care of itself:
- Pay every account on time, every month. This single habit affects a much larger share of your score than AAoA ever will.
- Keep utilization low across all cards, not just one. Aim to use a small fraction of your total available credit.
- Only open a new account when you actually need it, not to chase a rewards bonus you'll rarely use.
- Keep older no-fee cards open if there's no cost to maintaining them, since closing them can shrink both your available credit and your average age at once.
- Consider closing a card only when it carries a fee you can't justify or a security risk you can't ignore.
If you're planning to apply for a mortgage or auto loan in the next several months, hold off on opening or closing anything. Timing hard inquiries around a big application matters more than most people realize, and a fresh tradeline right before underwriting can work against you on two fronts at once.
Pro Tip: Set a recurring calendar reminder every quarter to pull a free credit report and scan your account list. Catching a card you forgot you had, one that's quietly aging in your favor, is one of the easiest wins in credit management.
Diversifying your account types can help your profile too, but only when it doesn't come at the cost of the age you've already built. Our breakdown on account diversity covers where that balance sits.
How an AI Credit Coach Helps You Balance Age, Utilization, and Timing
Juggling five cards in your head, remembering which one is oldest, which has a fee, which is closest to its limit, is exactly the kind of tedious tracking that causes people to make the wrong call. Such a tool can pull every card into one consolidated view so you can see account ages, balances, and due dates without opening multiple apps.
An AI-powered credit coach can flag when paying down a specific card protects your utilization ratio without you having to do the math yourself, and its credit health tracking can reveal whether an old, no-fee card is quietly doing more for your score than you realized before you consider closing it. For someone managing multiple cards who wants to protect both age and utilization at the same time, that kind of consolidated visibility solves a real, everyday blind spot.
FICO and VantageScore Don't Weigh Account Age the Same Way
FICO and VantageScore both consider how long you've had credit, but they don't treat it identically. FICO's length of credit history category sits around 15% of the score and includes AAoA, your oldest account's age, and time since your newest account opened, as CFPB's scoring breakdown lays out.

VantageScore groups age and credit mix together into a single category, rather than isolating length of history the way FICO does. That means a VantageScore calculation can weigh the combination of how long you've had credit and how varied your accounts are (cards, loans, mortgages) somewhat differently than a FICO calculation would for the exact same credit file.
The practical result: your FICO score and your VantageScore can move in slightly different directions after the same event, like opening a new card or closing an old one, because each model buckets the underlying inputs differently. Neither model publishes an exact AAoA number you need to hit. Both simply reward a longer, cleaner history and penalize a report full of very new accounts.
If you're watching your score ahead of a major purchase, check which model your lender actually pulls. A mortgage lender might rely on an older FICO version, while a free score from your bank's app might be VantageScore. Seeing a gap between the two isn't a red flag. It's just two different formulas reading the same file.
What Counts as a Good Average Account Age
There's no official cutoff that separates a "good" AAoA from a "bad" one. The CFPB is explicit that scoring models weigh payment history and balances far more heavily than account age alone, so chasing a specific number misses the point.
That said, patterns show up across score tiers in the way credit behaves in general. Consumers with scores in the exceptional range (typically reported around 800 and above) tend to have older, well-established accounts with years of on-time payment history behind them, simply because that kind of track record takes time to build. People newer to credit, or those rebuilding after missed payments, often show shorter average ages paired with the very late payments dragging their score down in the first place.
The relationship runs both directions. A long AAoA with a clean record supports a higher score, but a long AAoA can't rescue a score dragged down by high utilization or recent missed payments. Conversely, someone with only two or three years of credit history can still land a strong score if every payment has been on time and balances stay low. Age helps, but it's not a substitute for the fundamentals.
Rather than fixating on a target number of years, use your AAoA as a general health indicator. If it's climbing steadily because you're keeping old accounts open and not constantly chasing new credit, you're on the right track. If it's stuck low because you keep opening and closing cards, that's a pattern worth breaking, not a number worth panicking over.

Why Account Age Only Matters Alongside Your Other Credit Factors
AAoA doesn't operate in isolation. It sits next to credit mix (the variety of loan types you carry) and recent inquiries (how many times you've applied for credit lately), and the three interact in ways that can amplify or cancel each other out.
Take credit mix first. Experian and myFICO both list average account age, oldest account age, and time since a new account opened as the specific metrics scoring models check under length of history. A varied mix, say a mortgage, an auto loan, and a couple of cards, tends to pair well with a healthy AAoA because it usually signals someone who's managed different credit types responsibly over time. A thin file with just one or two cards can have a perfectly fine AAoA but still score lower simply because there's less to evaluate.
Recent inquiries complicate things further. Applying for several new accounts in a short window does two things at once: it adds hard inquiries to your file and, if approved, drags your AAoA down with fresh zero month tradelines. Neither hit is fatal on its own, but stacked together right before a mortgage or auto loan application, they can shave points off your score at the worst possible time.
The upshot: don't manage AAoA in a vacuum. A new card might nudge your average age down while simultaneously improving your utilization ratio by adding available credit, a genuine trade-off rather than a clear win or loss. Look at the whole file, not one metric in isolation, before deciding whether a change is worth making.
The Myths About Account Age That Cost People Points
The biggest myth is that AAoA is a magic number you should optimize above everything else. It isn't. Payment history and utilization move your score far more than a few months of average age ever will, and treating AAoA as the main lever leads people to make backwards decisions.
A second myth: closing a card immediately erases its positive influence on your score. It doesn't happen instantly. Closed accounts can stay on your report and continue factoring into your history for a period afterward, though the exact impact depends on your overall file.
A third misconception: opening new accounts is always bad for your score. It temporarily lowers AAoA, true, but it also raises your total available credit, which can improve your utilization ratio enough to offset the age dip. The net effect depends on your existing balances and how many accounts you already carry.
A fourth myth worth killing: that you should open accounts specifically to "season" them for a future loan. There's no shortcut that lets you fast forward an account's age. If you need credit, open it because you need it, and plan your timeline around when you'll actually apply for major financing, not around gaming a metric that carries less weight than the fundamentals you're neglecting instead.
How Marriage, Divorce, and Moving Can Shift Your Account Age
Life events change your credit file more than most people expect, and AAoA often moves as a side effect rather than the main event.
Marriage frequently brings joint accounts into the picture. Opening a new joint credit card or refinancing a mortgage together adds a fresh, zero month tradeline to both spouses' reports, which can pull the household's blended average down even if each partner individually had a long, clean history beforehand.
Divorce tends to work the opposite way. Closing joint accounts, or having an ex remove you as an authorized user, can strip years of history off your report all at once. If that joint account happened to be one of your oldest tradelines, its removal can spike your AAoA down sharply and catch people off guard months after the paperwork is finalized.
Relocation rarely touches AAoA directly, but the behavior that often accompanies a move does. New apartment applications, new utility accounts, sometimes a new auto loan for a longer commute, all of that activity can stack multiple new tradelines into your file within a short window, each one dragging the average down a little further.
None of these events are avoidable or even bad for your finances long term. The point is to recognize that a dip in your AAoA after a major life change is usually explainable, not a sign something went wrong. Give it time, keep paying on time, and the average will climb back up the same way it always does.
Stop Chasing the Age Number, Start Fixing What Actually Drives Your Score
Most credit advice treats AAoA like it's a lever you can pull for quick gains. It isn't. Spend your effort chasing a low utilization ratio and a spotless payment record, and your account age will quietly take care of itself over time.
Where conventional advice really falls short is the blanket rule to "never close an old card." Sometimes that's right. Sometimes a card with a fee you never use isn't worth preserving for a fractional age benefit, especially if it's not even your oldest account. The better question isn't "will this hurt my AAoA," it's "does this account still serve me, and what's the actual cost of keeping or closing it."
For anyone juggling several cards, the practical fix is visibility. Seeing every account's age, balance, and due date in one place makes it obvious which cards are worth protecting and which payments need attention this week. That clarity matters more than any single credit factor on its own.
— Grace K.
Manage Every Card's Age and Payment Timing in One Place
This type of app is built as an AI-powered credit card coach rather than a rewards optimizer, focusing on the key factors that affect your score: paying on time and keeping utilization low, while helping you understand how each card's age fits into the bigger scoring picture.
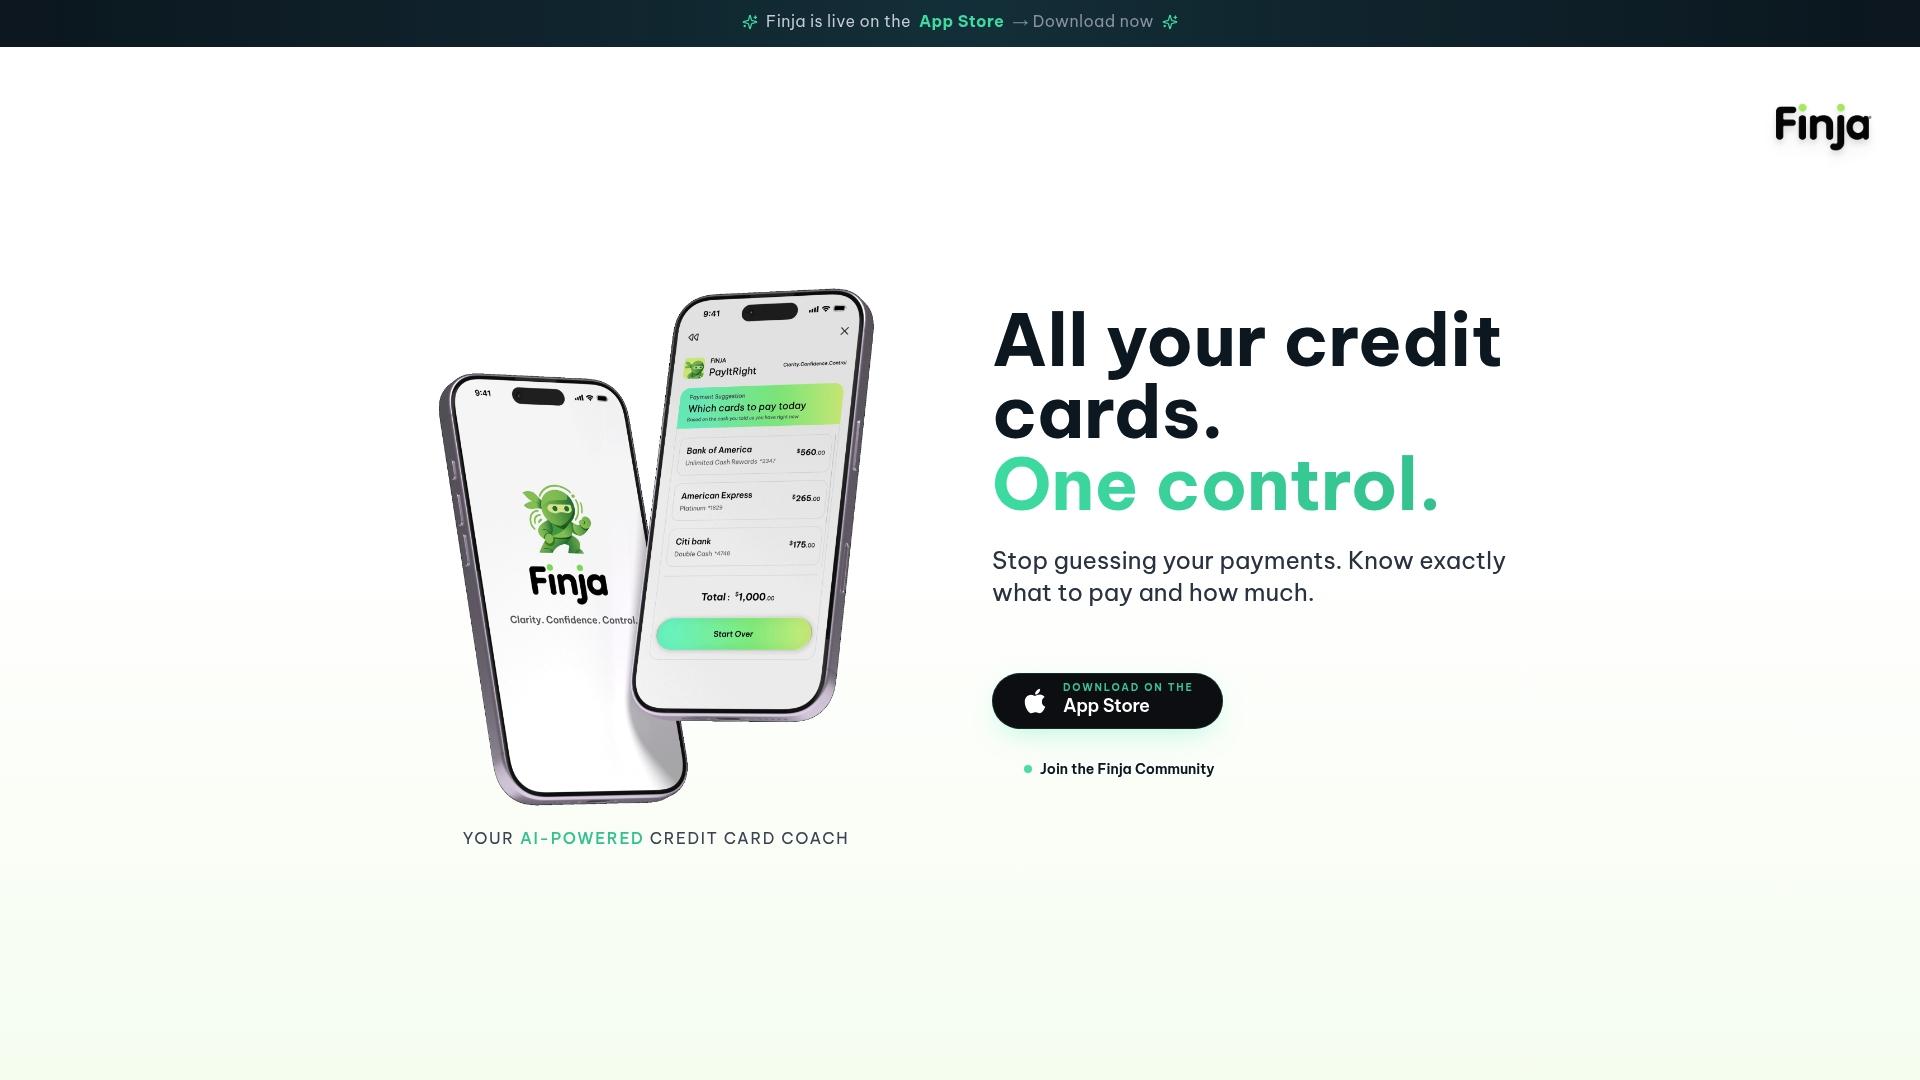
If you're carrying multiple cards and losing track of which one is closest to its limit or which one you opened most recently, such an app can consolidate every account into a single view so nothing slips through unnoticed. It's built for exactly this situation: multiple cards, real interest costs, and a credit score you'd rather protect than gamble with. Visit the Finja landing page to see how the coaching works for your specific set of cards.
Sources
- Understand your credit score | Consumer Financial Protection Bureau
- Building blocks: understanding credit scores (CFPB poster)
- How Does Length of Credit History Affect Credit Score? | Experian
FAQ
What Is a Good Average Age of Accounts?
There's no official "good" threshold for AAoA, since scoring models weigh payment history and utilization far more heavily than account age. Generally, a longer average paired with on-time payments supports a higher score, but a short history with perfect payments can still score well.
How Rare Is an 820 Credit Score?
Exceptional credit scores typically reflect years of consistent on-time payments, low utilization, and an established account history. There's no fixed AAoA requirement to get there. The score reflects the whole file, not one factor.
How Many Americans Carry Over $10,000 in Credit Card Debt?
A meaningful share of U.S. cardholders carry balances above that threshold, and high balances relative to credit limits hurt scores more directly than account age does. If that's your situation, paying down utilization will move your score faster than anything related to AAoA.
Does Closing a Card Immediately Hurt My Average Age?
Not immediately. Closed accounts can remain on your credit report for a period and continue contributing to your history, so the impact on AAoA often shows up gradually rather than all at once.
Can Finja Help Me Decide Whether to Keep an Old Card Open?
Yes. Finja's consolidated account view shows each card's age, balance, and fee status side by side, making it easier to see whether an old no-fee card is worth preserving before you decide to close it.